§1014at death
Stepped-up basis at death
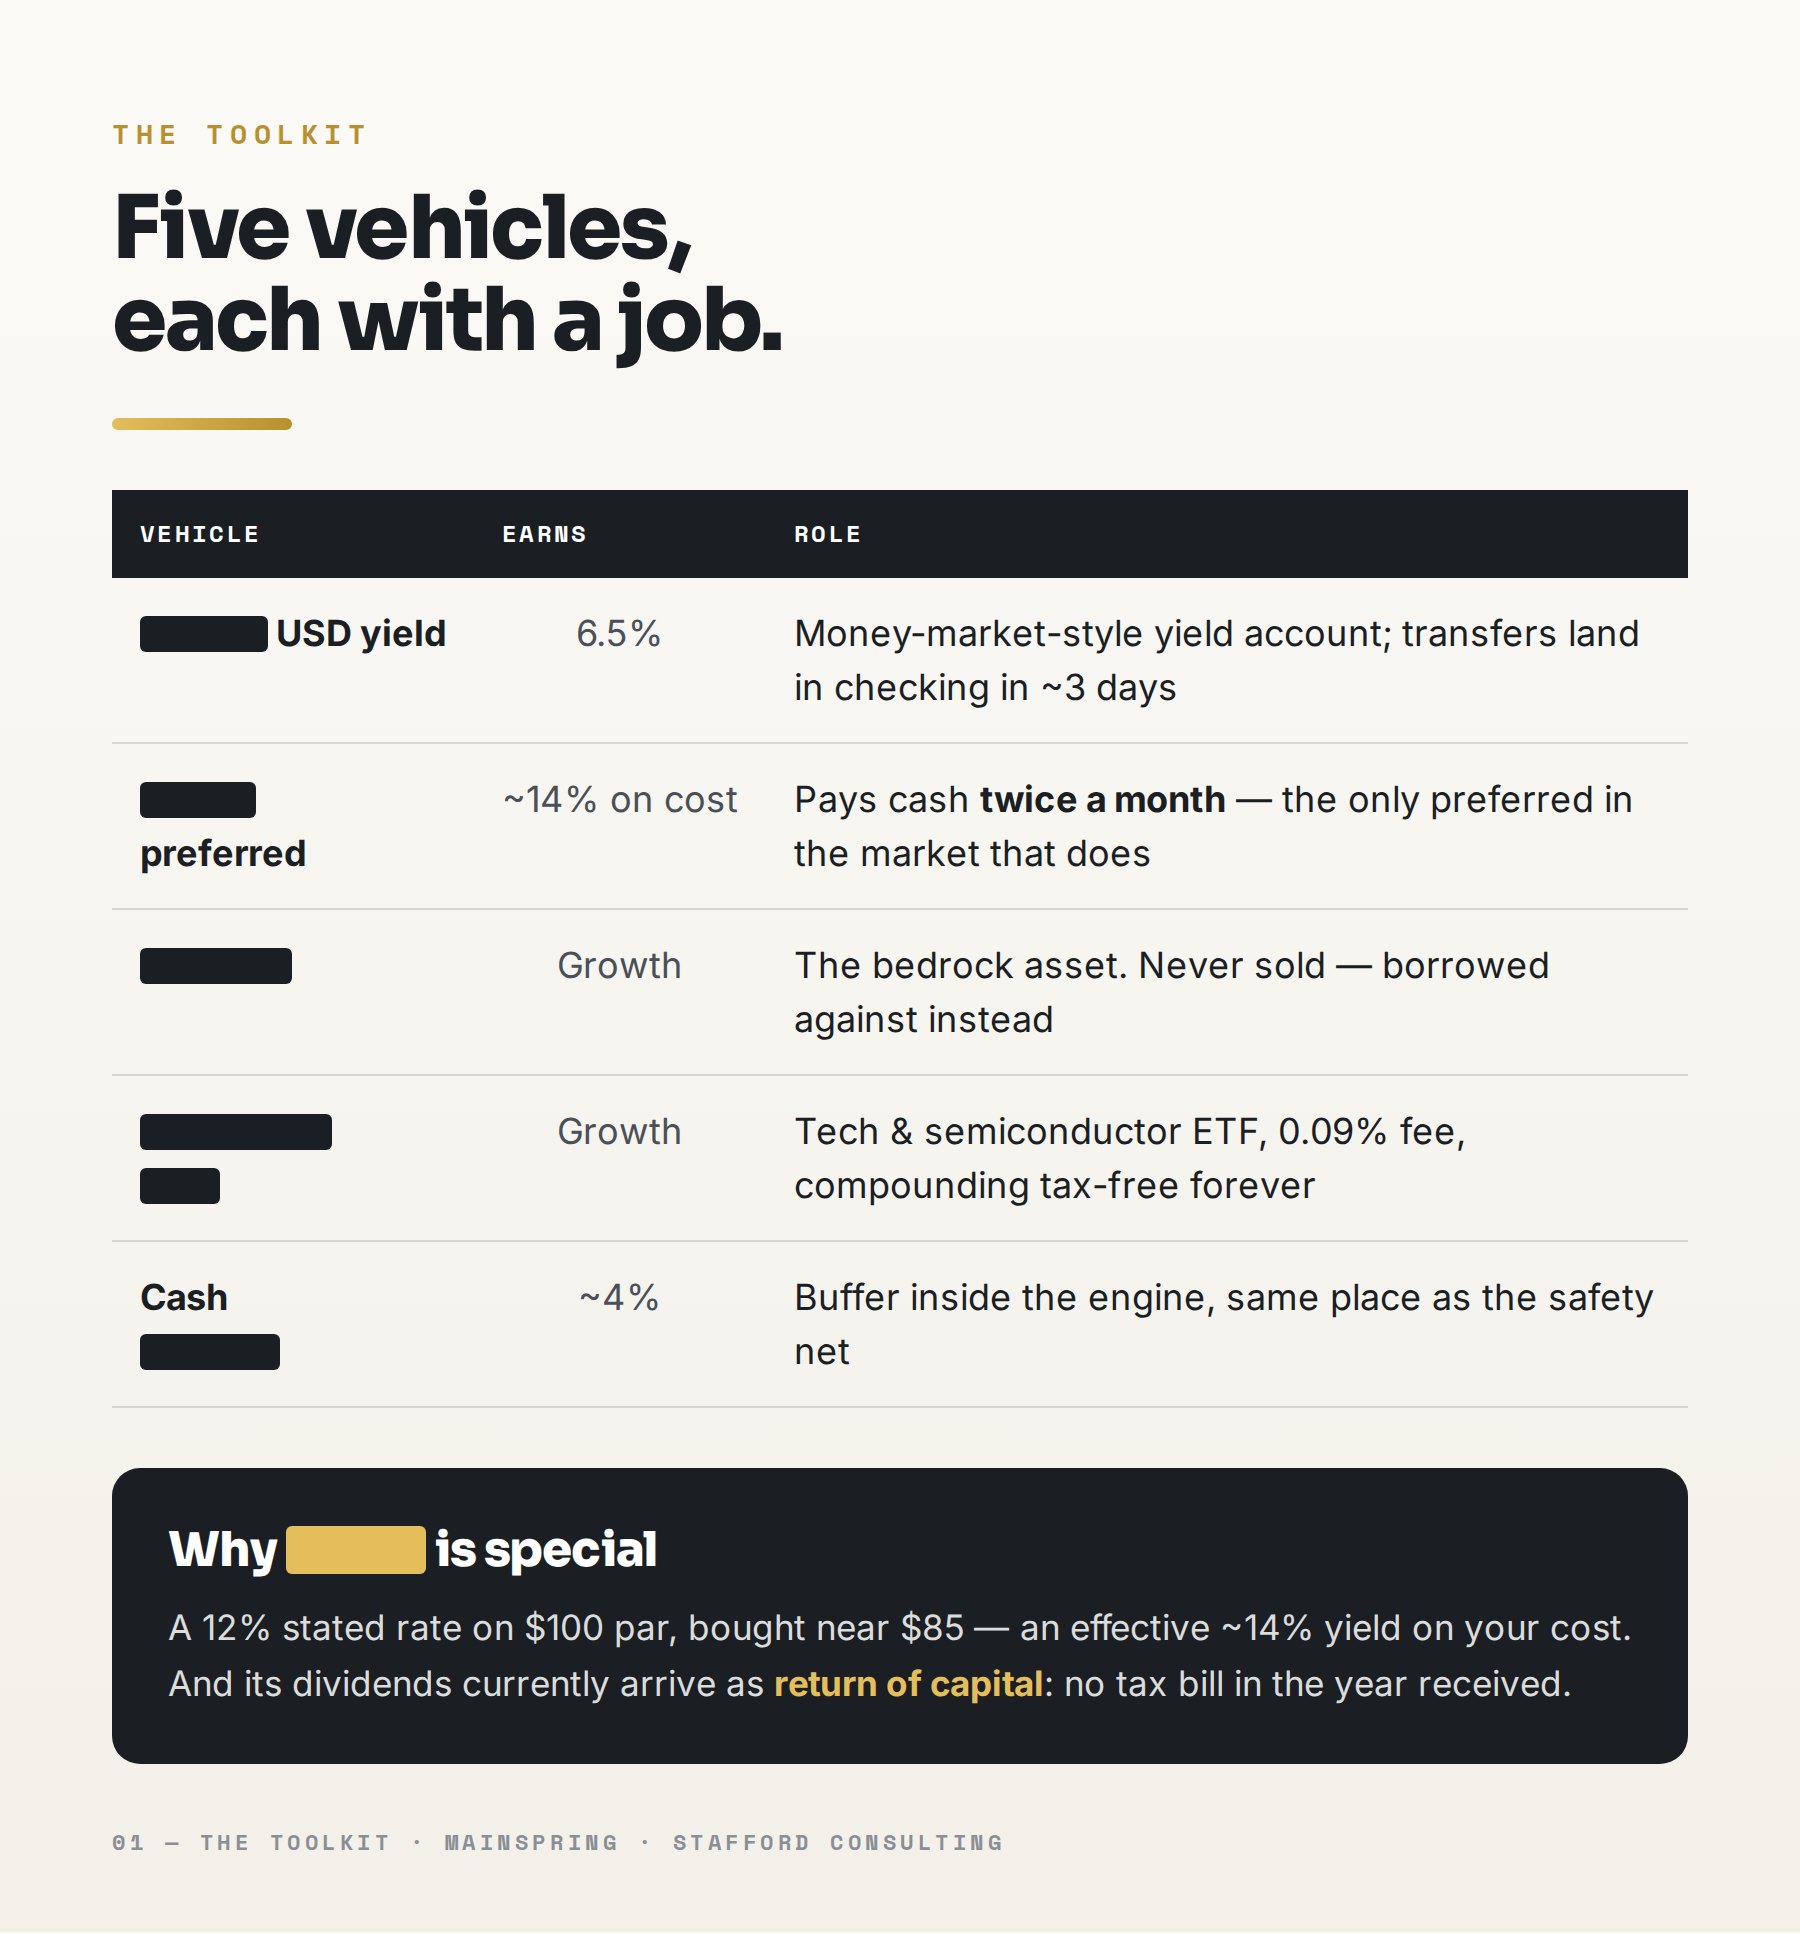
Most appreciated assets included in a decedent’s gross estate receive a basis adjustment to fair market value as of the date of death. Capital gain that accrued during the owner’s lifetime is eliminated rather than inherited — heirs take the asset at the adjusted basis and may sell with little or no capital gains tax.